

myEquifax
by Equifax Incorporated
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
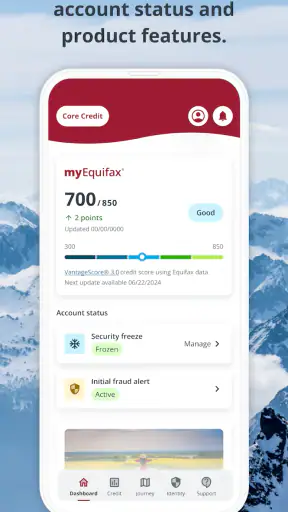
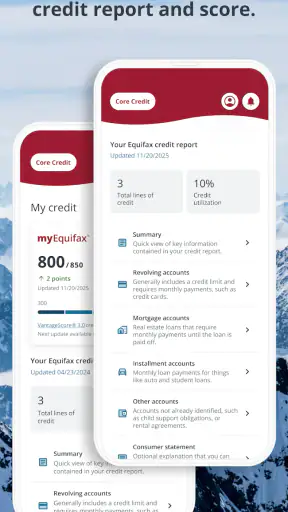
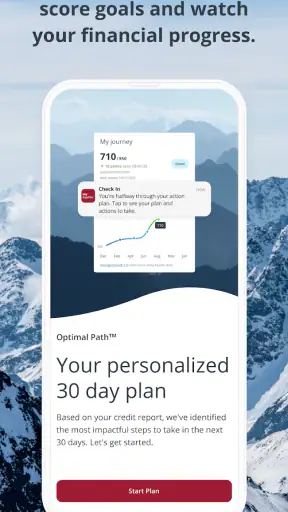
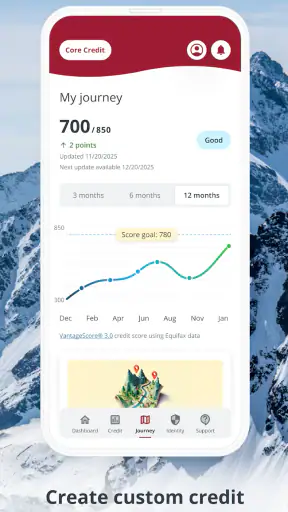
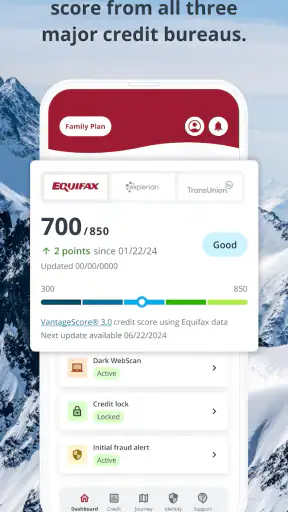
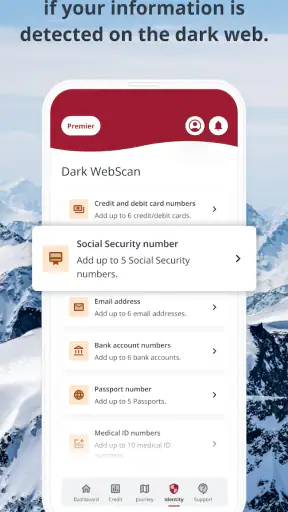
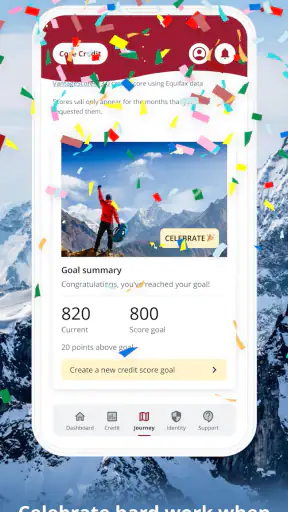
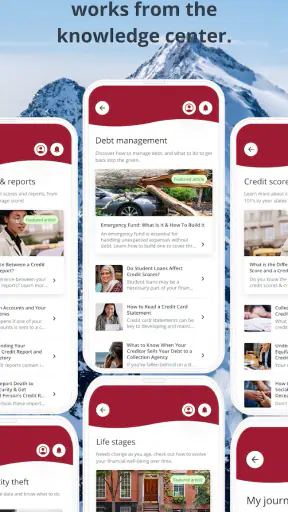
 Analysis by Getfullapps
I approached myEquifax as a practical finance app rather than something to open every day for entertainment. Its purpose is clear from the start: it is designed to help people begin or manage a credit-related routine from a phone. That makes it most relevant to anyone who wants a more direct way to stay aware of their credit journey without relying entirely on a desktop browser or scattered financial tools.
What I like about the app’s positioning is that it does not pretend to be a complete money-management replacement. It comes from Equifax Incorporated, a name directly associated with credit information, so the experience is centered on credit rather than budgeting, banking, investing, or bill payment. That narrower focus is important when deciding whether it deserves space on your phone.
The app is free to download, and that is the clearest value point I can verify. There is no purchase price attached to access itself, so a curious user can try it without committing money upfront. At the same time, free access should not be confused with a promise that every credit-related service or optional offering connected with Equifax is free. I would treat the app as a free entry point and read any screen involving a separate service, enrollment, or payment carefully before continuing.
How myEquifax fits into a real credit routine
In practical terms, I see this app as a central place for someone who wants to make credit awareness a habit. Instead of waiting until a loan, rental application, or credit-card decision forces you to think about your credit, the app encourages a more deliberate approach. That shift is useful because credit problems are often easier to address when noticed early rather than discovered during an urgent application.
A realistic example would be preparing to rent a new apartment. I would open the app before submitting applications, review the information available to me, and use that review to decide whether I need to investigate anything unusual. If something looks unfamiliar, I would record the account details and dates separately rather than trying to solve the entire issue while filling out a rental form. The advantage is not instant approval or a guaranteed outcome; it is having a clearer starting point before another company evaluates my application.
The same workflow can help before financing a vehicle or applying for a new card. I would use the app as an early check, then compare what I see with my own records, statements, and payment history. That second step matters. A credit app can organize access to information, but it should not replace careful document review or direct communication with a lender when a decision has real financial consequences.
For someone new to credit, the “start your credit journey” idea is especially approachable. A first-time user may not know which questions to ask or when credit deserves attention. Having a dedicated finance app can make the subject feel less abstract than reading general advice online. I would still expect to spend time learning what each item means, because a simple interface cannot remove the complexity of credit reporting.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What the free access means for value
Since the app itself is free, the value calculation is mainly about usefulness, trust, and consistency rather than saving a subscription fee. If it helps me check my credit-related information when I need it and keeps that process easier than using a browser, it can earn its place without requiring a purchase. That is a sensible proposition for cautious users who want to explore the service first.
There is also a practical benefit to avoiding an immediate financial commitment. Credit tools can sound essential when someone is worried about an application, but paying for a service under pressure is not always the right response. With free access to myEquifax, I can begin by understanding the available experience and decide whether it fits my needs before considering anything that might involve additional cost.
That distinction is worth keeping in mind: the app’s download price is free, while the broader value of any connected credit product depends on what a user chooses to use. I would not install it expecting every possible Equifax feature to be included automatically. I would install it to see whether its core access and organization are useful for my situation.
Where it is more useful than ordinary alternatives
The usual alternative is opening a mobile browser, searching for the Equifax site, signing in, and navigating from there. A dedicated app can be more convenient because it gives the task a fixed place on the phone. That small difference matters when the goal is to check credit periodically instead of postponing it because the process feels inconvenient.
Another alternative is a general-purpose personal finance app. Those apps may be better for budgets, spending categories, account balances, or savings goals. They can provide a wider view of daily money, but they are not automatically better for credit-specific attention. If my main question is about my Equifax-related credit journey, a focused app is likely less distracting than a dashboard filled with unrelated financial information.
On the other hand, a general finance service may be the better choice for someone who wants one place to manage a household budget and monitor several financial accounts. myEquifax should not be judged as a replacement for that wider toolkit. Its value comes from focus, not coverage of every financial task.
Small habits that make the app more useful
My first practical tip would be to use the app before an important financial event, not only after a problem appears. Checking ahead of a rental application, vehicle purchase, or new credit request gives me time to compare the information with my own paperwork. It also reduces the temptation to make a rushed decision based on a single screen.
My second tip is to keep a simple external note of anything that needs follow-up. I would write down the name of an unfamiliar account, the date I noticed it, and what document I need to find next. That turns a vague worry into a short investigation plan. The app can be the place where I notice an issue, while my notes and records help me handle it methodically.
A third useful approach is to separate monitoring from improvement. Seeing credit information does not automatically change it. Better credit decisions still depend on actions such as reviewing bills, avoiding missed payments, and understanding applications before submitting them. I would use the app to inform those decisions, not as a substitute for them.
Finally, I would avoid checking repeatedly in response to anxiety. A credit journey is usually more useful when it becomes a calm routine. Opening the app with a specific question—such as whether an account is familiar or whether my records match what I see—makes the session more productive than refreshing without a plan.
Where the experience may create friction
Credit information is sensitive, so the first hurdle is naturally trust. I would only use the app on a device I control and would take the sign-in process seriously. Convenience is helpful, but not at the expense of basic account security habits. A finance app is not the place for casual password reuse or leaving an account open on a shared phone.
Another possible source of frustration is that credit terminology can be difficult for newcomers. Even when an app presents information clearly, users may still wonder why an item appears, how a lender will interpret it, or what action is appropriate. I would not assume that a clean mobile presentation means every decision is self-explanatory. When the stakes are high, official explanations and direct support may still be necessary.
The focused nature of the app can also feel limiting. If I want to track spending, create a budget, compare bank accounts, or plan savings goals, I would need another tool. That is not a flaw in itself, but it affects the overall value. Someone hoping for an all-in-one money dashboard may find the experience too narrow.
I would also be careful about expecting immediate results. A credit app can help me observe and organize, but it cannot make a lender approve an application or erase the consequences of past financial behavior simply because I installed it. The right expectation is improved awareness and a more organized process.
Who is most likely to benefit
I think myEquifax is a strong fit for people who are beginning to pay attention to credit and want a dedicated starting point. It can also suit users preparing for a major application who prefer a mobile workflow instead of visiting a website each time. The free entry point lowers the barrier for both groups, especially when they are still deciding how much credit monitoring belongs in their financial routine.
It may be particularly helpful for someone who tends to ignore credit until a deadline appears. A dedicated icon can serve as a reminder that credit deserves occasional attention even when there is no immediate borrowing need. Used calmly, that habit can make future applications less intimidating.
I would be more cautious recommending it to a user who already has a comprehensive financial platform and wants to reduce the number of apps on their phone. If that person’s existing service already handles the exact Equifax-related task they need, adding another app may create duplication rather than value.
It is also not my first recommendation for someone whose primary goal is household budgeting. In that case, a capable budgeting app or banking tool may deliver more relevant value. myEquifax makes more sense when credit is the central question, not merely one small part of a broader financial dashboard.
Compatibility, maturity, and everyday usability
The app supports Android devices running version eight or later, which gives it a reasonably broad reach among Android users. It is also rated for Everyone, so its presentation is intended for a general audience rather than a specialist financial audience. That does not mean every credit decision is simple, but it does make the app approachable for adults who are just starting to learn how credit works.
It was released on April 25, 2025, and the current version is 1.11.0. I read that as a relatively new mobile experience rather than a product with a long-established app history. Newer software can feel more modern, but it can also mean that some users will encounter an experience still being refined. I would keep the app updated and judge it by whether the current version handles my essential tasks reliably.
The public response is encouraging without being a reason to skip personal evaluation. It holds an average rating of 4.6 from around ten thousand ratings, with 985 written reviews and more than 500 thousand installs. Those figures suggest that many people find it worthwhile, but they do not guarantee that every user will have the same experience. Finance apps are especially personal: a smooth check for one person may feel incomplete or confusing to another.
The developer shown for the app is Equifax Incorporated, which gives the product a direct connection to the Equifax brand rather than making it an unrelated third-party viewer. For me, that is relevant when deciding where to begin with Equifax-specific credit information. I would still verify that I am using the genuine app and pay attention during sign-in, because brand recognition alone should not replace careful installation habits.
My decision after weighing the tradeoffs
I would recommend trying myEquifax if you want a free, focused way to begin paying attention to your Equifax credit journey. Its strongest argument is not that it replaces every financial tool; it is that it gives credit a dedicated place in a mobile routine. For a person preparing for a rental, loan, or new credit application, that focus can be genuinely useful.
I would skip it if you are searching for budgeting, banking, investing, or complete household money management in one app. I would also skip adding it purely out of fear if you are not prepared to review information calmly and follow up through your own records. Installation by itself does not improve financial health.
My final view is positive but measured. The app is free, accessible on supported Android devices, and backed by a developer whose name is directly relevant to the service. Its best use is as an organized first stop: check what is available, compare it with your records, note anything that needs attention, and then take the appropriate next step. For anyone starting a credit routine, that combination of focused access and no upfront app price makes myEquifax worth trying.
Pros
- Free access to your Equifax credit report and score
- Credit monitoring alerts can flag potential changes quickly
- Identity protection tools help detect suspicious activity
- Simple dashboard makes credit information easy to review
- Useful educational resources explain credit factors and trends
Cons
- Some features require a paid subscription or eligible Equifax product
- Credit scores may differ from those used by lenders
- Identity verification can be inconvenient for some users
- Alerts may arrive after activity has already appeared on your file
- App usefulness depends on Equifax coverage in your country
FAQs for myEquifax
What is myEquifax and what can I use it for?
myEquifax is Equifax’s mobile and online service for managing personal credit information and identity-related tools. After signing in, users may be able to review their Equifax credit report, check available credit score information, receive account notifications, manage monitoring features, and access identity-protection resources. The exact features can vary by country, subscription, eligibility, and the specific Equifax service connected to your account.
Is myEquifax free to download and use?
The myEquifax app may be free to download, but not every feature is necessarily free. Depending on your location and account type, you may receive access to a free credit report or other basic services, while credit monitoring, identity protection, alerts, and additional reports may require a paid plan or trial subscription. Always review the pricing, renewal terms, and included benefits before entering payment details.
Is my personal and financial information secure in myEquifax?
myEquifax is designed to handle sensitive personal and financial information using account authentication and security measures intended to protect user data. However, no online service can eliminate every risk. Use a strong, unique password, enable available multi-factor authentication, keep the app updated, avoid signing in over unsecured public networks, and contact Equifax immediately if you notice unfamiliar activity or changes to your account.
Why can’t I access my credit report or credit score in myEquifax?
Access to a credit report or score can depend on your country, identity-verification status, subscription, account eligibility, and the information available in Equifax’s records. A failed verification attempt, mismatched personal details, temporary maintenance, or an outdated app can also prevent access. Check that your information is entered correctly, update myEquifax, and use Equifax’s official support channels if the problem continues.
What should I do if I find an error or suspicious activity in myEquifax?
If your report contains incorrect personal details, accounts, balances, or payment information, review the report carefully and use the dispute process provided by Equifax in your region. Gather supporting documents and keep records of your submission. If you suspect identity theft, change your password, secure related accounts, contact the relevant financial institution, and follow Equifax’s official guidance for fraud alerts, freezes, or identity-restoration assistance.











